Capacity Europe 2026: New technology, familiar challenges
After some time away from Capacity Europe, I returned to find an industry transformed by AI, cloud and digital infrastructure investment. Yet some of the biggest questions felt remarkably familiar - who captures the value this time round?
It's been a while since I've attended Capacity Europe. Walking back into the conference this week, I was struck by how much has changed, but also by how familiar many of the conversations felt. And, of course, it was great to be back amongst my tribe.
Over the years, I've seen the telecoms industry reinvent itself several times. From voice to data, from traditional networks to internet connectivity, from connectivity to cloud and digital infrastructure. Each transition brought new technologies, new competitors and new opportunities. It also brought a familiar problem: the companies investing in and operating the infrastructure weren't necessarily the ones capturing the greatest economic value from it.
Are we about to see the same thing happen again?
A familiar problem, on an unfamiliar scale
There was understandably a great deal of discussion about AI and the enormous investment flowing into the digital infrastructure needed to support it. I spoke with plenty of data centres, subsea cables, fibre networks, interconnection, computing capacity and power providers (I love the GeoPura product) are most are attracting eye=watering levels of investment.
B UT there were 3 things that are dangerous to cofuse.
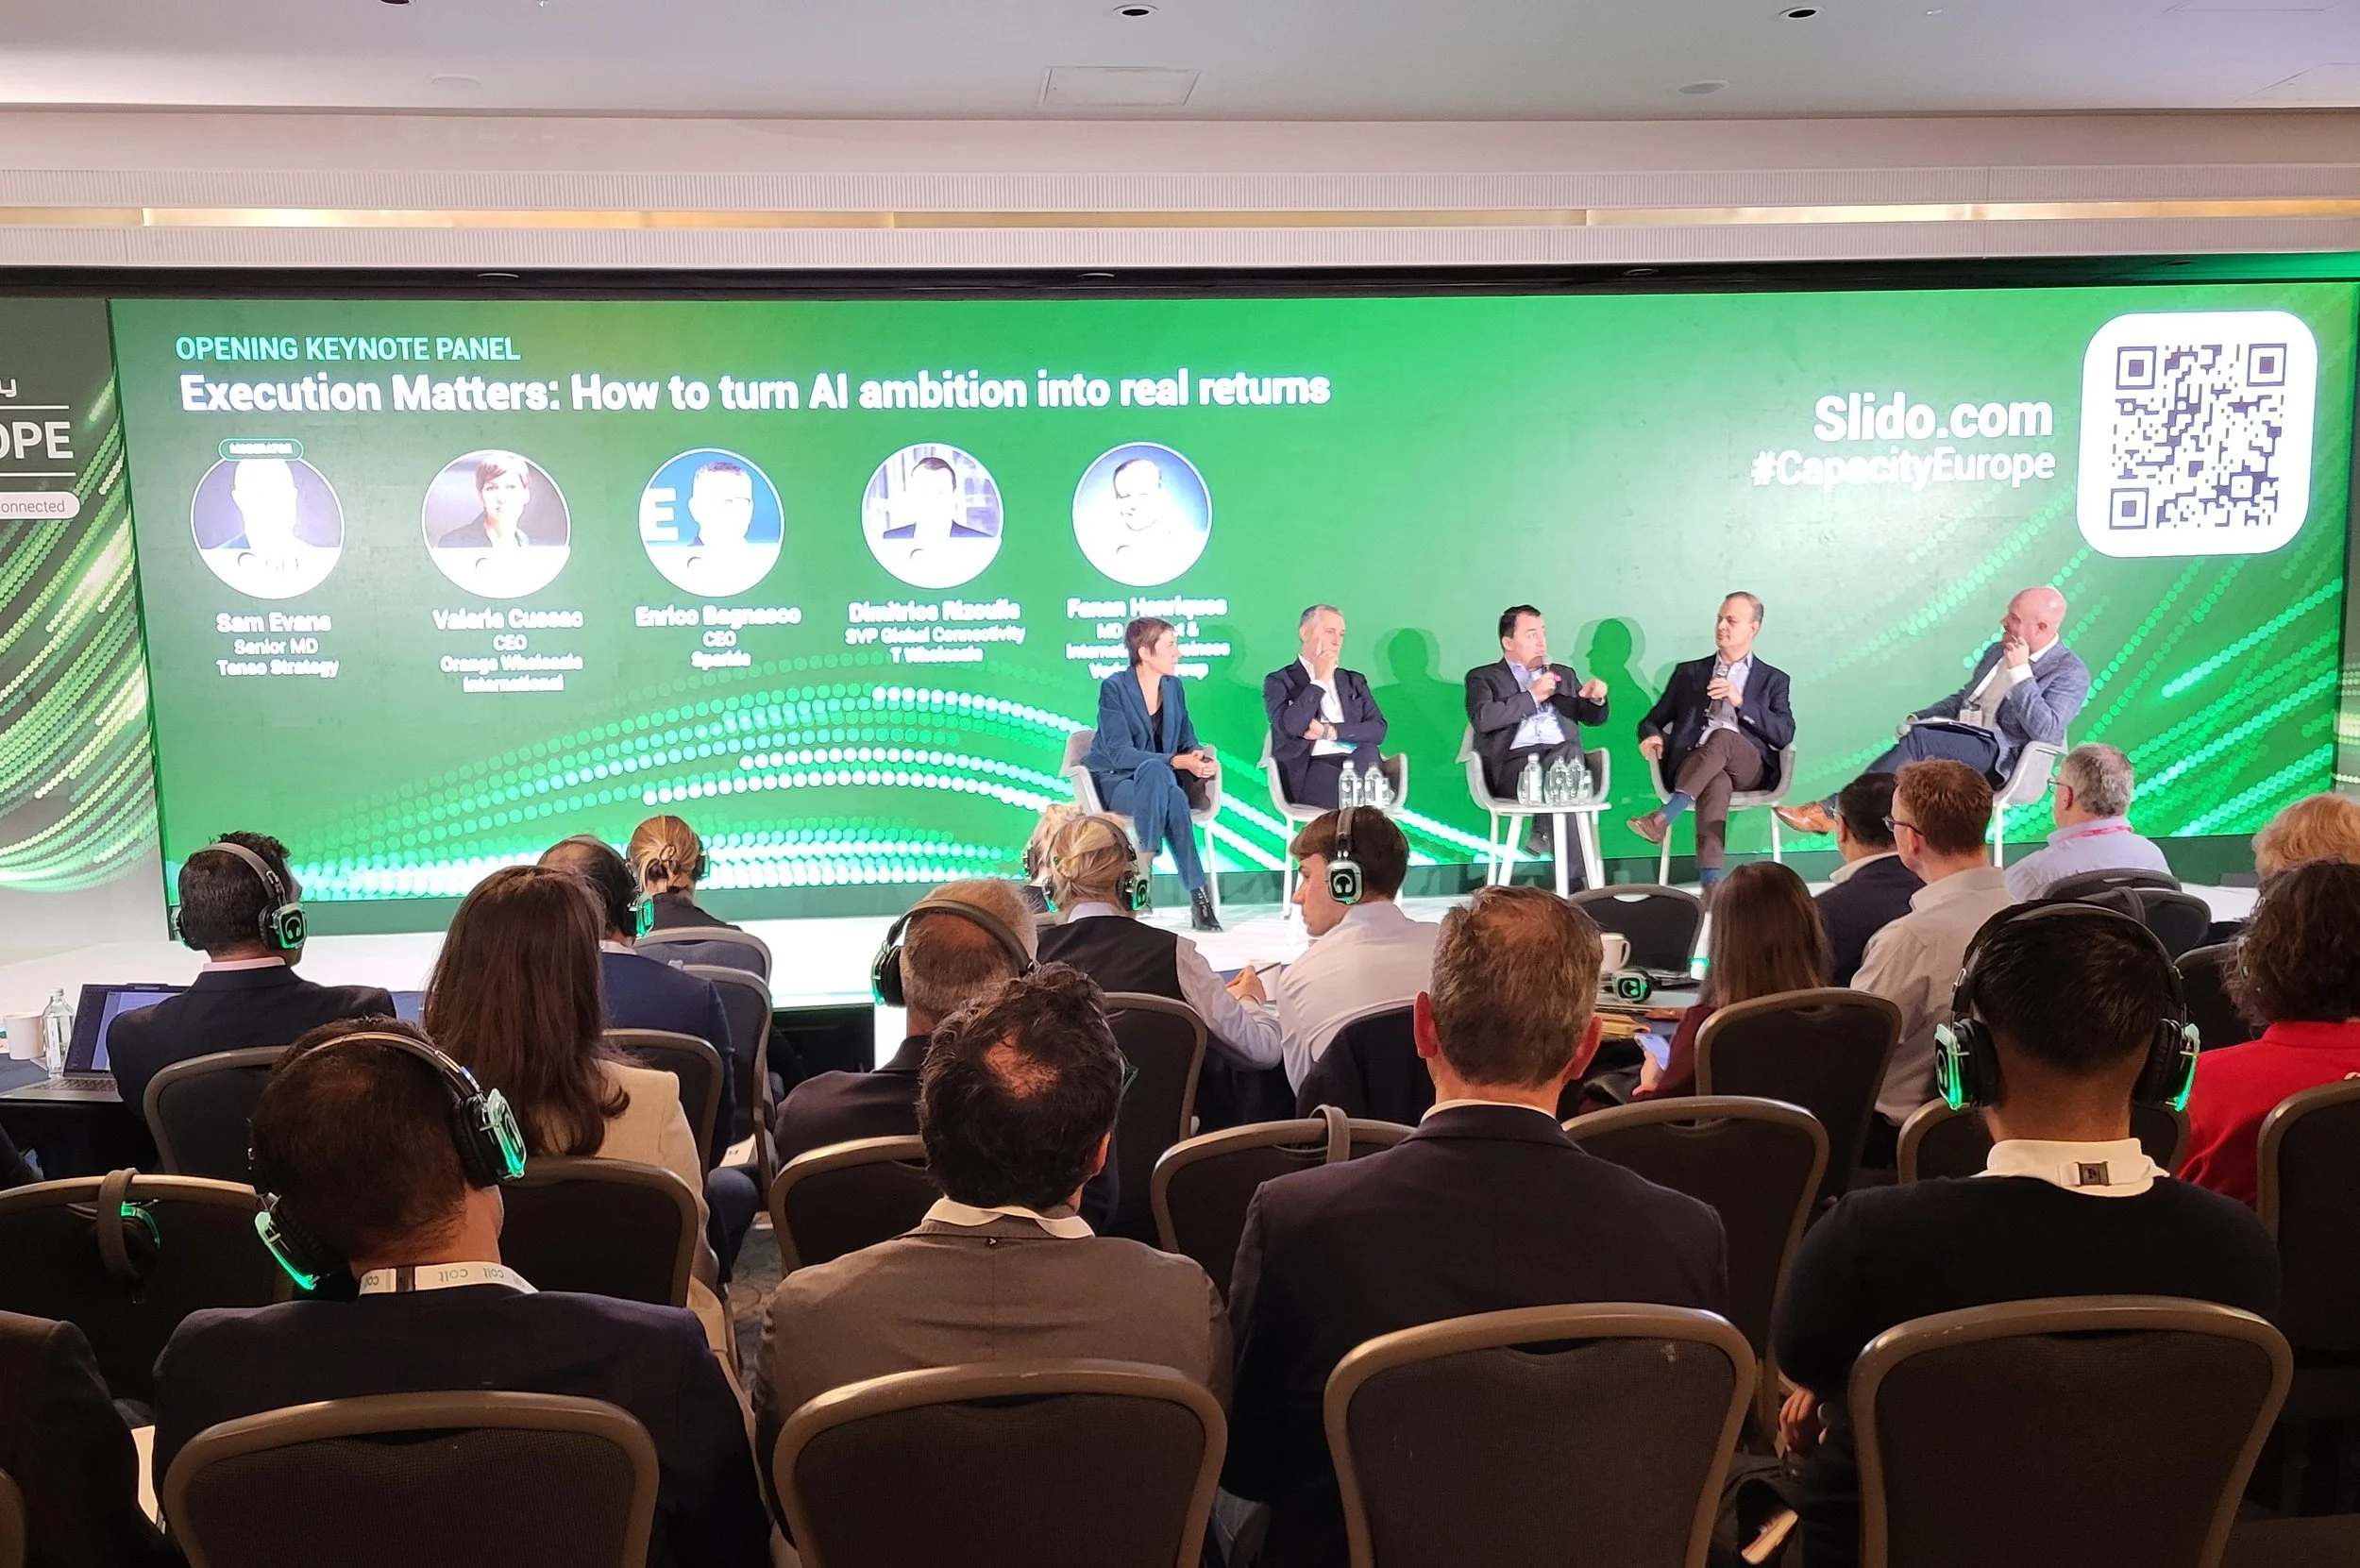
Capacity Europe 2026
1. The economic value an industry provides to society
2. The revenues it generates for the company
3. The financial returns for investors
And telecoms has seen this before. Remember the transition from wholesale voice to data some 25 years ago. Voice was becoming commoditised, margins were under pressure and value was shifting towards IP networks, internet services and new applications.
Then the growth of over-the-top services brought another wave of disruption. We carry the traffic, invest in networks and support the extraordinary expansion of the digital economy. Meanwhile, technology platforms built world beating businesses on top of that infrastructure. The industry survived but most of the economic upside was delivered elsewhere.
McKinsey made the same point in its February 2026 report early this year, The Telco Reinvention: How AI Can Fuel Value Creation, suggesting that AI is another inflection point, with operators once again facing the challenge of translating investment and technical capability into sustainable economic returns.
Is it different this time because the businesses driving demand for infrastructure are also investing in and controlling parts of that infrastructure themselves.
The hyperscaler question
Hyperscalers are changing the economics and ownership of digital infrastructure. Google, Microsoft, Meta and Amazon are major investors in the networks, subsea cables, data centres and computing infrastructure on which their businesses depend.
TeleGeography's analysis of submarine cable investment shows how this market has changed with private network operators accounting for an increasing share of capacity deployment.
For traditional network operators, this creates an uncomfortable question. If your largest customers finance, own and control the infrastructure they need, how much value remains available to the independent businesses that have historically supplied them?
I would say that it’s not all bad news and that the answer isn't necessarily less, across the board. AI is creating new requirements for high-capacity networks, geographical diversity, resilience, low-latency connectivity and secure access to distributed computing resources. Some of those requirements may make some infrastructure assets and capabilities substantially more valuable.
In the networking world, higher demand doesn't automatically produce higher margins because where there’s demand, there are assets and services are interchangeable and customers have significant buying power. Increased traffic may simply mean more investment without proportionate improvement in returns.
And here’s the rub. Businesses controlling genuinely scarce routes, critical interconnection points, reliable power, local market access or trusted customer relationships may find themselves in a much stronger position. These are the famous ‘bottlenecks’ everyones now talking about.
What will customers actually pay for?
Capacity tried to address this question, asking carriers where they thing they can retain defensible value in the AI stack, what customers will pay for beyond infrastructure, and who will ultimately control the AI customer relationship.
Naaz Bax was asking “Who Captures the Next Wave of Value?”
There is a temptation for network operators to move further into cloud integration, managed services, security, network intelligence and AI-enabled solutions (Liquid Telecom becomes Liquid Intelligent Technologies?? FFS)
Marketing a move into adjacent services doesn't give differentiation or profitability. Those markets have powerful competitors of their own. There’s no reason why the winnersnecessarily need to move further up the technology stack. Physical infrastructure can be an excellent business when it delivers something customers genuinely need and cannot easily obtain elsewhere.
Stop the engineers for designing the commercial propositions and listen to the market. What does the business control that customers particularly value? What can it deliver more reliably, securely or efficiently than its competitors? Where does it have pricing power? And who actually owns the customer relationship? (well done WIOCC)
As AI evolves from a technology people interact with into systems that can act, transact and make decisions autonomously, software will become a significant customer of infrastructure and services. That will change how capacity, computing resources, security, identity and network intelligence are purchased and consumed.
But the principle remains the same: businesses need a defensible reason to get paid, and a commercial model that allows them to retain sufficient value.
Has the industry's story kept pace?
There's another dimension to all this which I’ve written about before. Over the years I've worked with businesses undergoing change through acquisitions, international expansion, investment, new technologies and evolving customer demands. The recurring challenge is that the business changes faster than the story being told about it.
A company that was once primarily a connectivity provider may now own valuable infrastructure, serve different customers, operate in new markets or offer a much broader range of capabilities. But I’ll bet it’s brand and market positioning, value propositions and communications will still be anchored in what it used to be.
Customers, partners and investors need to understand where the business is going, what makes it different and how it intends to create and capture value. I know it’s not all in the story and that even the most convincing narrative won’t compensate for an uncompetitive business model. The underlying proposition has to be real, differentiated and commercially credible.
But think abot the strong business that will struggle if the market doesn't understand what it offers or why that offer matters. As the boundaries between telecoms, cloud, computing, data centres and digital infrastructure continue to blur, I’m betting that this challenge will become increasingly important.
The ability to explain clearly what a business is becoming, why customers should choose it and where future value will come from is a strategic communications issue, not simply a marketing exercise.
Another inflection point
I’m encouraged by the scale of opportunity and, at the same time, struck by how familiar some of the challenges are. There is clearly enormous investment going into the infrastructure that will underpin the AI economy but investment alone is not evidence of future profitability (as I’ve seen in the energy sector) and rising demand for infrastructure doesn't tell us who will reap the rewards.
businesses will benefit from owning assets that become increasingly scarce or strategically important. Others will create value through integration, intelligence, resilience, trust or stronger customer relationships. And some will find themselves investing heavily in infrastructure letting others take the economic upside.
By 2029, I suspect the most successful businesses won't be the ones that have built the most infrastructure. They will be those that have worked out precisely where the choke points are, how they can create differentiated value and how to capture a fair share of it. And most importantly, my bit, how to make that value clear to the market.
If we're building the infrastructure for the next digital economy, how do we make sure we capture more of the value it creates this time round?